Comparative Evaluation of ARIMA, LSTM and Hybrid ARIMA-LSTM Models for Forecasting the Apple Inc. Stock Price
DOI:
https://doi.org/10.33003/fjs-2026-1021-6370Keywords:
Apple Stock Price, ARIMA, LSTM, Hybrid, Time Series ForecastingAbstract
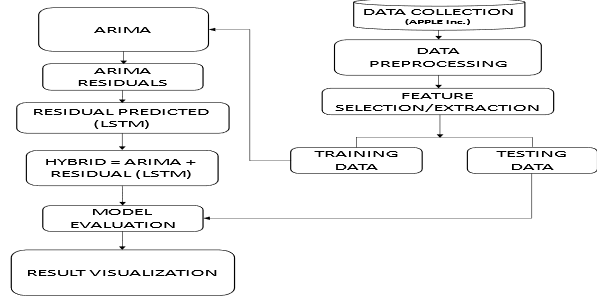
ABSTRACT: Accurate stock-price forecasting remains challenging due to the complex, nonlinear, and volatile nature of financial time series. This study developed and evaluated a hybrid ARIMA-LSTM model for forecasting Apple Inc. stock prices using 11,107 observations spanning December 1980 to January 2025. The dataset, obtained from Kaggle, used Close price as the target variable and Open, High, Low, Adjusted Close, and Volume as input features. Three forecasting models were evaluated: ARIMA(1,1,1), a stacked LSTM comprising two LSTM layers with 50 units each followed by two Dense layers, and a hybrid ARIMA-LSTM model that combines ARIMA-based linear forecasting with LSTM residual learning. The data were divided chronologically into 80% training and 20% testing sets, and model performance was assessed using MAE, MSE, RMSE, MAPE, and R². ARIMA achieved the best overall performance, with an MAE of 1.3328, MSE of 4.3612, RMSE of 2.0884, MAPE of 1.25%, and R² of 0.9990. The LSTM recorded an MAE of 3.7500, MSE of 34.3950, RMSE of 5.8650, MAPE of 2.60%, and R² of 0.9920. The hybrid model achieved an MAE of 1.3610, MSE of 4.4570, RMSE of 2.1110, MAPE of 1.30%, and R² of 0.9990.
References
Abir, S. I., Saimon, S. I., Saha, T., Sarwer, M., Hasan, M., Sultana, N., & Islam, I. (2025). Comparative analysis of currency exchange and stock markets in BRICS using machine learning to forecast optimal trends for data-driven decision making. Journal of Economics, Finance, and Accounting Studies, 7(1), 26–48. https://doi.org/10.32996/jefas.2025.7.1.3
Adekoya, A. F., Nti, I. K., & Weyori, B. A. (2021). Long short-term memory network for predicting exchange rate of the Ghanaian cedi. FinTech, 1(1), 25–43. https://doi.org/10.3390/fintech1010002
Ajumi, O., & Kaushik, A. (2017). Exchange rates prediction via deep learning and machine learning: A literature survey on currency forecasting. International Journal of Science and Research, 7(12), 1252–1262. https://www.academia.edu/download/81531908/ART20193849.pdf
Bandara, K., Bergmeir, C., & Smyl, S. (2020). Forecasting across time series databases using recurrent neural networks on groups of similar series: A clustering approach. Expert Systems with Applications, 140, Article 112896. https://doi.org/10.1016/j.eswa.2019.112896
Burkaltseva, D., Niyazbekova, S., Borsch, L., Jallal, M. A. K., Apatova, N., Nurpeisova, A., … Zhansagimova, A. (2022). Methodological foundations of the risk of the stock markets of developed and developing countries in the conditions of the crisis. Journal of Risk and Financial Management, 15(1), Article 3. https://doi.org/10.3390/jrfm15010003
Cappello, C., Congedi, A., De Iaco, S., & Mariella, L. (2025). Traditional prediction techniques and machine learning approaches for financial time series analysis. Mathematics, 13(3), Article 537. https://doi.org/10.3390/math13030537
Carosia, A. E. D. O., da Silva, A. E. A., & Coelho, G. P. (2025). Predicting the Brazilian stock market with sentiment analysis, technical indicators and stock prices: A deep learning approach. Computational Economics, 65(4), 2351–2378. https://doi.org/10.1007/s10614-024-10636-y
Chauhan, J. K., Ahmed, T., & Sinha, A. (2025). A novel deep learning model for stock market prediction using a sentiment analysis system from authoritative financial website’s data. Connection Science, 37(1), Article 2455070. https://doi.org/10.1080/09540091.2025.2455070
Friday, I. K., Pati, S. P., Mishra, D., Mallick, P. K., & Kumar, S. (2025). CAGTRADE: Predicting stock market price movement with a CNN-attention-GRU model. Asia-Pacific Financial Markets, 32(2), 583–608. https://doi.org/10.1007/s10690-024-09463-w
Gajiwala, C. (2025). Stock market analysis using deep learning. Journal of Computer Science and Technology Studies, 7(2), 559–566. https://doi.org/10.32996/jcsts.2025.7.2.59
Gawer, A., & Cusumano, M. A. (2014). Industry platforms and ecosystem innovation. Journal of Product Innovation Management, 31(3), 417-433. https://doi.org/10.1111/jpim.12105
Ibraeva, Z. E., Bektemyssova, G., & Ahmad, A. R. (2023). Fuzzy model for time series forecasting. Scientific Journal of Astana IT University, 2023, 93-102. https://doi.org/10.37943/13eotu7482
Kaggle (2025). Apple Stock Market Historical Data (1980-2025) https://www.kaggle.com/datasets/umerhaddii/apple-stock-data-2025
Khashei, M., Bijari, M., & Hejazi, S. R. (2012). Combining seasonal ARIMA models with computational intelligence techniques for time series forecasting. Soft Computing, 16(6), 1091-1105. https://doi.org/10.1007/s00500-012-0805-9
Lawal, M. A. M., Abdulrauf, A., Delmut, R. D., & Tohomdet, L. K. Evaluating the Effectiveness of ARIMA and LSTM Models in Predicting USD/NGN Trends. Machine learning, 13, 14. https://iccait.com.ng/wp-content/uploads/2026/05/12_Mohammed_Lawal_et-al.pdf
Loubochkin, M. M. (2018). Economic growth and company stock pricing in the global stock market. Вестник Санкт-Петербургского университета. Экономика, 34(3), 396. https://doi.org/10.21638/spbu05.2018.303
Malgwi, Y. M., Abba, S. A., & Pam, N. G. (2026). A Persistence-Driven Naïve-LSTM Residual Hybrid Model for Forecasting the United States Dollar-Nigerian Naira Exchange Rate. FUDMA Journal of Sciences, 10(18), 162-170.
Martínez, F., Frías, M. P., Pirez-Godoy, M. D., & Rivera, A. J. (2022). Time series forecasting by generalized regression neural networks trained with multiple series. IEEE Access, 10, 3275–3283. https://doi.org/10.1109/ACCESS.2022.3140377
Nenkov, D. (2024). “The magnificent seven” technology stocks and their impact on the S&P 500: A review 4 years later. Finance, Accounting and Business Analysis, 6(2), 180–195. https://www.ceeol.com/search/article-detail?id=1293489
Odion, P. O., Lawal, M. M., & Abdulrauf, A. (2025). A comparative analysis of an enhanced hybrid model for predicting Dollar against Naira exchange rate using deep learning and statistical methods. Journal of Computing Theories and Applications, 2(4), 511–522. https://doi.org/10.62411/jcta.12513
Sajal, A., Chy, M. S. K., Jamee, S. S., Uddin, M. N., Khan, M. S., Gharami, A. K., & Ahmed, M. (2025). Forecasting bank profitability using deep learning and macroeconomic indicators: A comparative model study. International Interdisciplinary Business Economics Advancement Journal, 6(6), 8–20. https://doi.org/10.55640/business/volume06issue06-02
Wang, M. (2024). Do new products affect a company’s share price? An event study of Apple SSRN. http://dx.doi.org/10.2139/ssrn.5567219
Zhang, G. P. (2003). Time series forecasting using a hybrid ARIMA and neural network model. Neurocomputing, 50, 159–175. 10.1016/S0925-2312(01)00702-0
Zhang, W., Li, J., & Li, Y. (2023, December). A novel loss function considering the distance between forecasting and historical values in financial time series forecasting models. In Proceedings of the 5th Management Science Informatization and Economic Innovation Development Conference (pp. 8-10). https://doi.org/10.4108/eai.8-12-2023.2344823
Downloads
Published
Issue
Section
Categories
License
Copyright (c) 2026 Alhaji Baba Nyako, Sandra Ahmadu Asabe

This work is licensed under a Creative Commons Attribution 4.0 International License.